
Most Trusted Salt Lake City Mortgage Lender
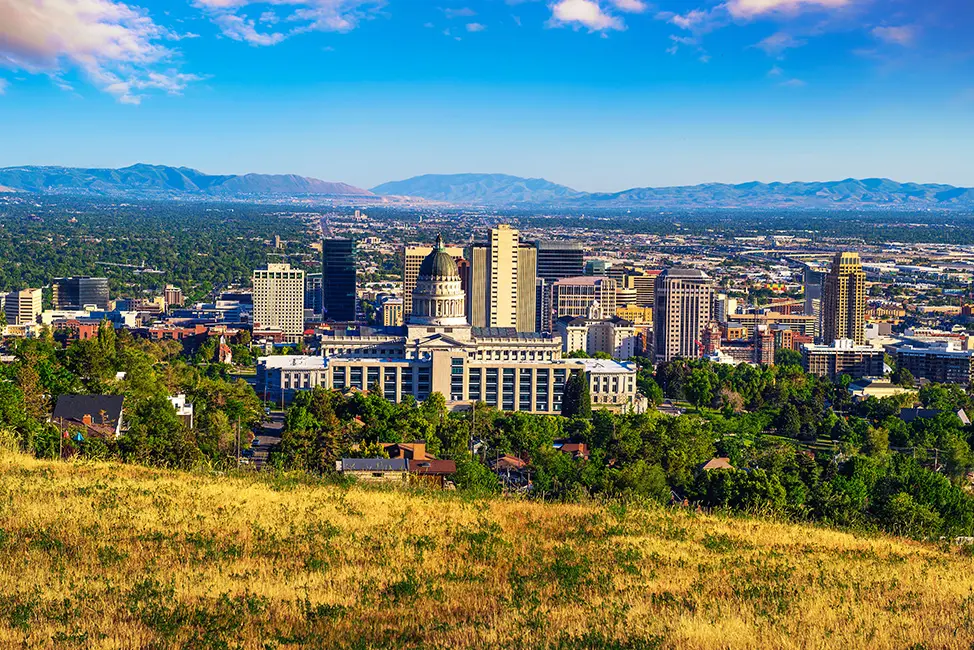
Loan Remedy is a licensed mortgage broker in Salt Lake City, based at 2005 E 2700 S, Suite 100. We’ve closed loans for Utah buyers since January 2019, and our clients have left us 319 Google reviews with a 5.0-star rating.
If you’re comparing a mortgage broker in Salt Lake City against a big bank or an online lender, here’s the short version of what we do differently. You get our personal cell phone numbers. We answer evenings and weekends. Our goal is a pre-approval within one hour of receiving your complete application and documents. Our typical closing is 14 days or less.
No hidden fees. No call centers. Just a broker who has personally closed 1,500+ loans and a team that closed more than 200 in the last 12 months alone.
Why Work With a Local Salt Lake City Mortgage Broker
Online lenders quote rates from three time zones away. They’re learning the Utah market from a computer screen. We live in it.
Since 2019, we’ve built working relationships with real estate agents, title companies, and other professionals across the valley. Agents who have worked with us know our process, our communication style, and our commitment to getting loans to the closing table. In a multiple-offer situation, that familiarity gives your offer added credibility.
There’s also the practical stuff. You can meet us in person at our office. You can text us at 8pm on a Saturday when a house hits the market, because that’s when houses hit the market. And when something unusual comes up with a property, we don’t just accept the first answer. On one triplex purchase, we called the county ourselves, confirmed the property was grandfathered as residential, and saved our client from an unnecessary commercial loan.
A local broker also shops your loan across multiple lenders instead of selling you one bank’s products. More options usually means better pricing and a better fit.
Your Loan Options in Salt Lake City
We work with nearly every loan type a Utah buyer might need. Here are the most common ones.
Conventional Loans: A strong fit for buyers with solid credit who want flexible terms. Down payments start at 3%, and you can remove mortgage insurance once you build 20% equity.
FHA Loans: Built for buyers with smaller down payments or credit challenges, starting at 3.5% down. For 2026, the FHA loan limit in Salt Lake County is $637,100 for a single-family home (source: HUD, 2026). We once used a high school transcript to satisfy FHA’s employment history rule for an 18-year-old buyer. More on that below.
VA Loans: Zero down payment for eligible veterans and service members, with no monthly mortgage insurance. We know the VA underwriting handbook well enough to document exceptions other lenders miss, including self-employment income with less than two years of history.
First-Time Buyer Programs: Utah offers real help for first-time buyers, and most lender websites barely mention it. We walk you through what’s available and whether it actually fits your situation. Details in the next section.
Buying elsewhere in the valley? We also lend in Millcreek and across all of Salt Lake, Utah, Davis, Weber, Summit, Wasatch, and Washington counties.
Utah First-Time Buyer Programs
Utah Housing Corporation is the state’s housing finance agency, and it offers first-mortgage programs and down payment assistance designed for first-time and moderate-income buyers.
These programs can be a great fit for certain buyers. They also carry specific eligibility requirements and guidelines on income, purchase price, and credit, and the assistance is a loan with its own terms, not free money.
That’s why we don’t push these programs on everyone. We take the time to determine whether they actually make sense for your situation. Sometimes Utah Housing is the best path to keys. Sometimes a standard FHA or conventional loan costs you less over time. We’ll show you the comparison and let you decide.
If you want a plain-English walkthrough of your options, get pre-approved, and we’ll cover it on the first call.
Neighborhoods We Serve in Salt Lake City
Sugar House: Early 1900s bungalows and Tudors mixed with newer condos near the business district. Popular with buyers who want walkability, which keeps competition steady.
The Avenues: Historic Victorian and cottage homes on compact lots north of downtown. Older housing stock means appraisals and inspections need a lender who won’t panic at a 120-year-old foundation.
Rose Park: Post-war starter homes on the city’s northwest side, and still one of the more affordable pockets in Salt Lake City proper.
Liberty Wells: Brick bungalows and cottages just south of Liberty Park, drawing buyers who want classic character close to downtown.
Ballpark: Named for Smith’s Ballpark, with a mix of small single-family homes, townhomes, and condos. Condos come with extra financing steps, and we know how to navigate them.
Millcreek Border: Our office sits close to the Salt Lake City and Millcreek line, so we lend on both sides. If you’re shopping that area, see our Millcreek page.
How Our Rates and Quotes Work
Start with Find My Rate. Answer a few questions about your purchase or refinance and get a quote with no impact to your credit score.
As a broker, we shop your scenario across multiple lenders and show you the strongest options we find. We’ve intentionally structured our business to make less on each transaction so we can pass better pricing to you. And if a qualified competitor offers a better rate, bring it to us. We’ll match it when possible.
We won’t promise to beat every lender on every loan. Nobody honest can. What we promise is competitive pricing, complete transparency, and no surprises at closing.
Real Clients, Real Outcomes
Denied at 18, Closed in Under Two Weeks: A young buyer came to us after another lender denied his FHA loan, saying he lacked the required two-year employment history. He’d been in high school. FHA guidelines allow education to count toward that history, so we requested his transcripts, documented the qualifying history, and closed his loan in under two weeks.
Told “No” By Multiple Lenders, Approved with a Joint VA Loan: A family found us through our Google reviews after several lenders said they couldn’t qualify. They were close to giving up. In our first detailed conversation, we learned the husband and his father would both be living in the home, and both had VA eligibility. That opened a strategy no one had presented: a joint VA loan combining their entitlements. We structured it, and the family got their home.
Neither story required bending a guideline. Both required a lender who actually read the file.
Already own a home? The same approach applies to refinancing in Salt Lake City.
What Clients Say
Courtney Graf
Chris and Sofija rocked it out of the park on our refinance over the Christmas Holiday break. We feel so fortunate to have found Loan Remedy through a referral from Dr. Kay at Back on Track Chiropractic.
We were under contract in one day and approved in two. Best possible rate, most competitive closing costs, nearly immediate responses, savings where ever possible and just stellar humans all around. We will be recommending them to everyone we can!
Thank you so much for your hard work team!!
Seth Merrill
Chris worked with us on a mortgage for a recent move. What a seamless experience. From the very first conversation I was impressed with his professionalism and knowledge of mortgage finance. He was tireless – creative, responsive, technically excellent, and able to secure a better rate for us than the other mortgage professionals we spoke with. Someone I will look forward to working with again.
Salt Lake City Mortgage FAQ
How much down payment do I need in Salt Lake City?
It depends on the loan. Conventional loans start at 3% down, FHA at 3.5%, and VA loans require nothing down for eligible veterans. Utah Housing Corporation programs can also help with down payment costs for qualified buyers. We’ll show you which option costs the least overall.
What credit score do I need to buy a home?
FHA loans allow lower scores than most loan types, with 580 the common threshold for 3.5% down. Conventional loans generally start around 620. If your score is borderline, talk to us before assuming you can’t qualify. Guidelines have more flexibility than most borrowers are told.
How long does closing take?
Our typical closing is 14 days or less from application to keys. We’ve closed an FHA purchase in under two weeks for a buyer who was denied elsewhere. Speed comes from personally reviewing your documents upfront rather than relying only on automated systems.
Do you charge hidden fees?
No, we’re transparent about our rates, fees, and loan costs from the beginning, so there are no surprises at closing. You’ll know exactly what you’re paying and why before you commit to anything.
Are you available on weekends?
Yes, clients get our personal cell phone numbers and can call, text, or email evenings and weekends. Buying a home doesn’t happen on a 9-to-5 schedule, and many of the biggest decisions happen after hours. We’re reachable when they do.
What’s the difference between a broker and a bank?
A bank offers only its own loan products. As a broker, we shop your file across multiple lenders and bring back the best pricing and fit we find. One application, multiple lenders competing, and a licensed local expert guiding the process.
Can I get pre-approved without a hard credit pull?
You can get a rate quote through Find My Rate with no impact to your credit score. A full pre-approval requires a credit check, and we’ll tell you exactly when that happens. Our goal is a pre-approval within one hour of receiving your complete documents.
What areas do you serve?
All of Salt Lake County, plus Utah, Davis, Weber, Summit, Wasatch, and Washington counties. Loan Remedy is licensed in 12 states, and Zach is personally licensed in 9, so we can often help even if you’re buying outside Utah.
Did you know that Loan Remedy is licensed to all your Utah mortgage needs? Check out our other locations: Ogden, Provo, Millcreek, Orem, and St. George. Call us today to lock in the best mortgage rate in your area.
Zach Coombs is President & Managing Broker of Loan Remedy, NMLS #1118518, with 13 years of mortgage industry experience and over 1,500 loans personally closed. Loan Remedy LLC, NMLS #1827478.